Super Micro Computer Deep Dive in Growth
One of the major stocks leading the market today is
(NASDAQ:SMCI).
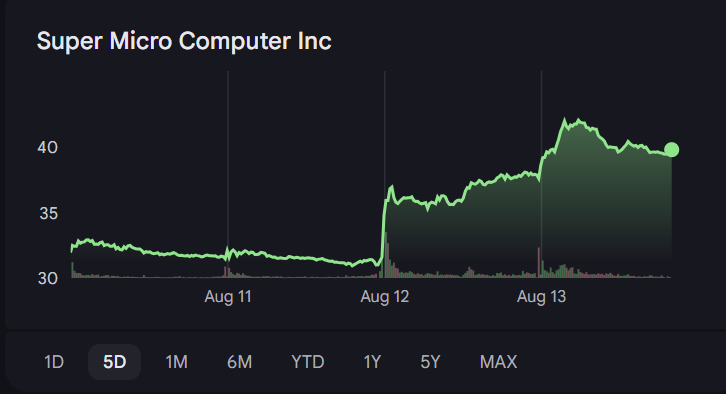
Why the Stock is Moving Up
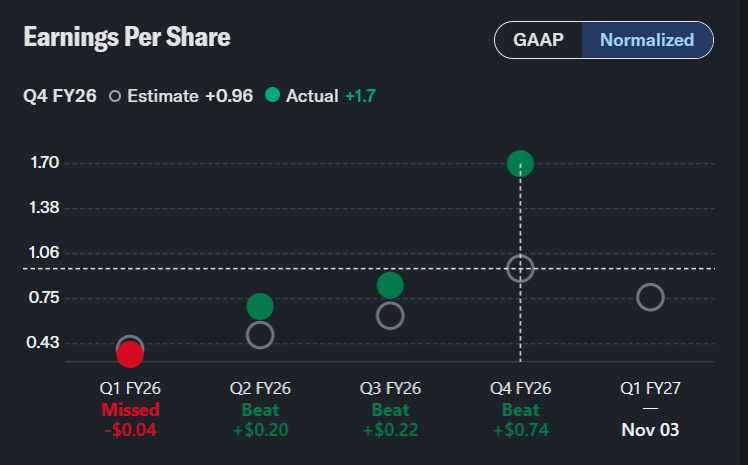
Blockbuster Earnings: NASDAQ:SMCI reported quarterly earnings of $1.70 per share, which significantly beat Wall Street consensus estimates of $0.68 per share.
Massive Revenue Surge: The company generated $11.12 billion in quarterly revenue, doubling its $5.76 billion performance from the prior-year period due to sustained AI infrastructure demand.
What to Look For
When analyzing a fast-moving growth stock like NASDAQ:SMCI, evaluate these core factors:
Earnings Quality & Guidance: Always check if revenue growth matches net income growth or if expanding margins are driving the upside.
AI Infrastructure Spending: Because NASDAQ:SMCI relies heavily on server installations, broader hardware demands and chip supply directly impact their pipeline.
Valuation Trajectory: Rapidly rising stocks can quickly hit overbought territory. Use forward metrics like the PEG ratio to verify whether the earnings acceleration justifies the price premium.
The order book is the crux of it. SMCI is one of the fastest-to-market builders of AI server racks (Nvidia GPU-based systems), and hyperscalers/cloud providers are still in aggressive AI infrastructure buildout mode. Analysts framed the quarter as proof that the AI capex cycle isn't slowing — Goldman Sachs and Mizuho both raised price targets on the print, citing AI demand. Rosenblatt raised its target to $45, noting the $60B order disclosure alone exceeded its full prior FY27 revenue estimate for the entire year.
The skeptics and this is the part worth paying attention to
The stock's move is not unanimous. This is a genuinely split tape:
BofA raised its price target to $33 (from $28) but kept an Underperform/Sell rating, saying flatly that current margins are "not sustainable" their view is competitive and cost pressure will erode that 17.6% gross margin back down over coming quarters.
Citi gave a "Hold and High-Risk" rating despite also hiking its price target.
TipRanks shows the Street consensus sitting at Hold (roughly 3 Buy / 8 Hold / 2 Sell), not a broad-based Buy unusual for a stock up double digits on the day.
The most historically accurate analyst on the name (per TipRanks' track record) has a Sell rating with a $15 target, implying over 50% downside from even yesterday's close a reminder that today's price action reflects one very good quarter, not analyst consensus on fair value.
What to actually watch going forward
Margin durability: this is the single biggest debate. The bear case rests entirely on whether 17%+ gross margins hold or get competed away (Dell, Lenovo, and others are also building AI racks). If margins stabilize near this level over the next 2-3 quarters, the bear case largely loses its footing. If they compress back toward the low-teens "durable baseline" some analysts model, today's move looks overdone.
Order-book-to-revenue conversion: $60B in orders is only as good as SMCI's ability to actually finance, build, and ship it. This is a company with historically thin margins and heavy working-capital needs (inventory, receivables) — converting backlog to cash flow, not just topline, is the real test.
The DOJ overhang: the indictment of co-founder Wally Liaw remains unresolved and is a lingering governance risk that doesn't show up in the earnings numbers.
Dilution risk: there's a planned ~$7B capital raise on the table against a market cap that was around $26-27B before today's pop — that's meaningful potential dilution investors need to size against the growth story.
Short interest: SMCI was among the top 10 most-shorted stocks going into this print, per Investing.com's analysis, so part of today's magnitude may reflect short covering rather than pure fundamental re-rating — worth watching if the move holds or fades over the next few sessions once the squeeze dynamic settles.