Kratos Defense & Security Solutions (NASDAQ:KTOS) — Deep-Dive Financial & Strategic Analysis
Kratos Defense & Security Solutions specializes in high-priority national security technology, focusing heavily on unmanned systems, hypersonic propulsion, space domain awareness, and cyber security. The company has increasingly transitioned from a niche defense developer into a high-rate production platform.
Financial Performance & Growth Track
Kratos reported stellar Q2 2026 earnings on August 4, 2026, demonstrating rapid top-line growth that exceeded Wall Street estimates.
Revenue Growth Acceleration: Q2 2026 revenue came in at $458.8 million, representing an impressive 30.5% year-over-year increase from Q2 2025's $351.5 million. Consolidated organic revenue grew 19.1%.
Upgraded Outlook: Based on strong execution, management raised its full-year 2026 revenue guidance to between $1.75 billion and $1.81 billion (up from initial projections), signaling organic growth of 18% to 23% over 2025.
Backlog Visibility: Total backlog has built up to $2.08 billion ($1.57 billion funded). Their trailing 12-month book-to-bill ratio stands at 1.3x with a massive $15 billion pipeline of upcoming bids and proposals.
Core Business Segments
1. Kratos Government Solutions (KGS)
This segment is currently Kratos's primary growth driver, jumping 36.4% YoY to $379.7 million in Q2 2026.
Hypersonics Ramping: Kratos's hypersonic target and rocket support business generated $200 million in 2025 and is on track to hit $400 million in 2026, with targets of $700 million+ by 2027 following key program wins like Kraken and Nemesis.
Propulsion Dominance: Through partnerships with GE Aerospace, Kratos is scaling turbojet and small engine production to act as a crucial second-source supplier for the military's Joint Air-to-Surface Standoff Missile (JASSM). They plan to ramp production capacity to 3,000 jet engines annually by 2027.
2. Unmanned Systems
Generating $79.1 million in Q2 (8.1% organic growth), this segment captures the most market excitement via tactical low-cost drones.
Flagship Drones: Their autonomous XQ-58A Valkyrie drone continuously hits key multi-use milestones, most recently completing missionized electronic-warfare and command-and-control tests for the U.S. Marine Corps.
The Investment Dilemma: Opportunities vs. Risks
Key Opportunities
Alignment with Modern Warfare Priorities: Pent-up global demand for affordable, autonomous, "attritable" (expendable) tech benefits Kratos's specific product lineup over traditional, expensive legacy defense primes.
Dual-Use Expansion: Kratos is adapting its military drone autonomy for commercial applications, including recent revenue-generating autonomous trucking and platooning runs.
️ Main Risks & Concerns
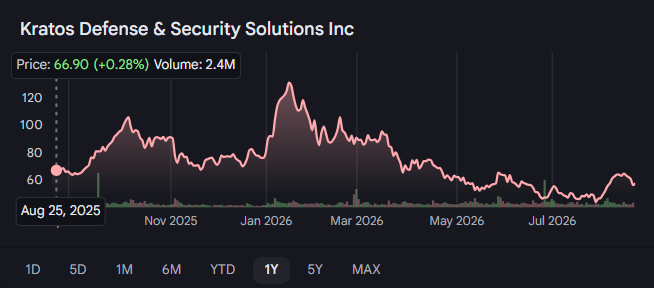
Extreme Valuation: Trading at a trailing P/E ratio over 330x and a market capitalization of $10.84 billion, the stock is heavily pricing in future growth. Some intrinsic models suggest the price reflects a premium over immediate free cash flow capabilities.
Margin and Free Cash Flow Strain: Despite high revenue growth, GAAP net profit was only $4.4 million for the quarter. Kratos is heavily investing ahead of demand—projecting $125–$135 million in 2026 capital expenditures—which creates near-term operational cash strain.
Recent Insider Selling: Heavy execution of executive stock options and insider selling in mid-August 2026 has induced slight short-term consolidation in the stock price.
Overall, Wall Street remains highly bullish with an average price target sitting around $105.62, viewing Kratos as an increasingly vital, scaled production platform for the modern Department of Defense.